Battery-Electric Cars Pass Petrol in EU Market as Registrations Reach 22.7%
Battery-electric cars claimed 22.7% of EU registrations through September 2026, moving ahead of petrol while hybrids remained the top choice.
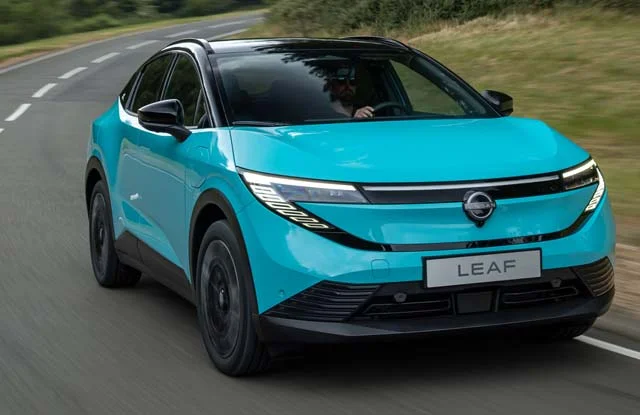
The powertrain ranking in the EU’s new-car market has changed: battery-electric cars moved ahead of petrol during the first nine months of 2026. They accounted for 22.7% of registrations, compared with 21.2% for petrol. Hybrids stayed in front, but the figures show how quickly the balance is shifting among buyers.
From January through September, 1,931,465 new battery-electric cars were registered across the EU. That was a 6.6 percentage-point increase in market share from 16.1% in the same period a year earlier. Total new passenger-car registrations rose 5.7% year to date, so the electric gain came in a growing market rather than one that was simply shrinking around it.
For drivers comparing powertrains, the headline is a change in relative popularity, not a complete handover. Petrol registrations still numbered 1,802,078, and hybrid-electric cars remained the largest category by a wide margin. But electric cars’ rise, alongside growing plug-in hybrid volumes, means that charging capability is becoming relevant to a much larger share of new-car buyers.
Four markets account for most electric registrations
France posted the strongest growth among the markets highlighted, with battery-electric registrations up 79.1%. Germany recorded a 58.1% increase, Denmark rose 40.3%, and Belgium grew 15.7%. Together, those four countries made up 64% of EU battery-electric registrations through September.
That concentration matters when reading a regional total. The 22.7% share describes the EU as a whole, while the national growth rates show that adoption is moving at different speeds. A strong increase in France or Germany can have considerable weight in the aggregate because these markets contribute so many registrations. The figures provided don’t explain the individual choices behind each increase, so they don’t establish whether price, vehicle availability, purchase support or other factors drove growth in a particular country.
For automakers, the spread suggests the value of having electric models available across several price points and vehicle types, while tailoring sales efforts to different national markets. For buyers, registration shares offer useful context about what other customers are choosing, but they don’t answer practical questions such as purchase price, access to charging, driving range or running costs. No model-level or ownership data is included in these totals.
Hybrids retain the lead
Hybrid-electric cars remained the EU’s most popular powertrain, taking 36.3% of new registrations. Their 3,090,530 registrations leave them well ahead of battery-electric cars in volume, even as the fully electric category gains share. Italy and Spain supported hybrid growth, with registrations increasing 20.8% and 20.5%, respectively. Germany was up 4.9%, and France edged up 0.6%.
The comparison points to two different kinds of momentum. Battery-electric cars recorded the more striking shift in ranking, while hybrids held the largest slice of the market. Hybrids can appeal to buyers who want some electrification without relying on external charging; however, the registration figures don’t distinguish among hybrid system types or describe how owners use them. They show the market result, not the daily experience behind it.
Plug-in hybrids add to the chargeable share
Plug-in hybrids reached 860,257 registrations in the nine-month period, lifting their market share to 10.1% from 9% a year earlier. Italy’s registrations rose 72.4%, Spain’s increased 34.7%, and Germany recorded growth of 13.7%.
Battery-electric cars and plug-in hybrids together represented 32.8% of new EU registrations. Put another way, nearly one in three newly registered cars in the period could be connected to an external power source. That combined figure is a broad measure of the market’s chargeable portion; it doesn’t mean every plug-in hybrid is charged regularly or that all drivers have comparable access to charging.
For shoppers weighing a plug-in hybrid against a fully electric car, this data can put the options in market context, but it can’t settle the choice. The article’s figures contain no comparison of vehicle prices, electric range, fuel consumption or charging infrastructure. Those details remain central to ownership and should be assessed model by model.
Petrol and diesel lose share
Petrol registrations fell 19.1% to 1,802,078, and petrol’s market share dropped from 27.7% to 21.2%. Every major EU market recorded a double-digit decline: France fell 36.1%, Germany 22.7%, Spain 19%, and Italy 16.4%. The decline is large enough to push petrol below battery-electric cars in the year-to-date ranking.
Diesel continued to contract as well. Registrations were down 19.5%, leaving diesel with 7.1% of the market, compared with 9.3% a year earlier. Together, the petrol and diesel figures mark a clear loss of ground for the two conventional fuel categories in this period.
The practical takeaway is a market with three distinct signals: hybrids lead by volume, battery-electric cars have crossed ahead of petrol, and plug-in hybrids are adding to the share of cars that can be charged. With new passenger-car registrations up 5.7% through September, the electric gain stands out against broader market growth. The next useful measure will be whether battery-electric momentum continues across more national markets, while hybrids preserve their substantial lead.